Can you start a SIP with just ₹500? Yes, a ₹500 monthly SIP can be a simple way to begin investing in mutual funds, provided the selected scheme accepts that minimum amount. The amount may be small, but starting early can help you develop a regular investing habit. In this guide, you will learn how to start a SIP with ₹500 in India, complete your KYC, choose an appropriate fund category, set up your monthly auto-debit and understand what a ₹500 SIP could potentially grow into over time.
Table of Contents
- Why ₹500 is Enough to Start
- What Can ₹500 a Month Grow Into?
- Step 1: Complete Your KYC
- Step 2: Set a Clear Goal for This SIP
- Step 3: Pick a Fund Category That Suits a Small SIP
- Step 4: Choose a Direct Plan on a Platform or the AMC App
- Step 5: Set Up the SIP and Auto-Debit Mandate
- Step 6: Confirm Your First Instalment
- Step 7: Stay Consistent — and Step Up Later
- How Rupee Cost Averaging Works: A ₹500 Example
- Common Mistakes With Small SIPs
- Frequently Asked Questions
Why ₹500 is Enough to Start
Most people delay investing because they're waiting to have "enough" money to start. A ₹500 SIP removes that excuse entirely — it's small enough to not disrupt your monthly budget, yet large enough to build the habit of investing before you're tempted to spend the money elsewhere. The amount matters far less than the consistency: someone who invests ₹500 every month for ten years without fail will usually end up ahead of someone who waits to invest a "meaningful" amount and never quite starts. Many mutual fund schemes allow SIP investments starting at ₹500, but the minimum amount varies by scheme. Always check the current scheme information or the AMC's official website before investing. For free investor education, AMFI's Mutual Funds Sahi Hai campaign is a useful next read.
What Can ₹500 a Month Grow Into?
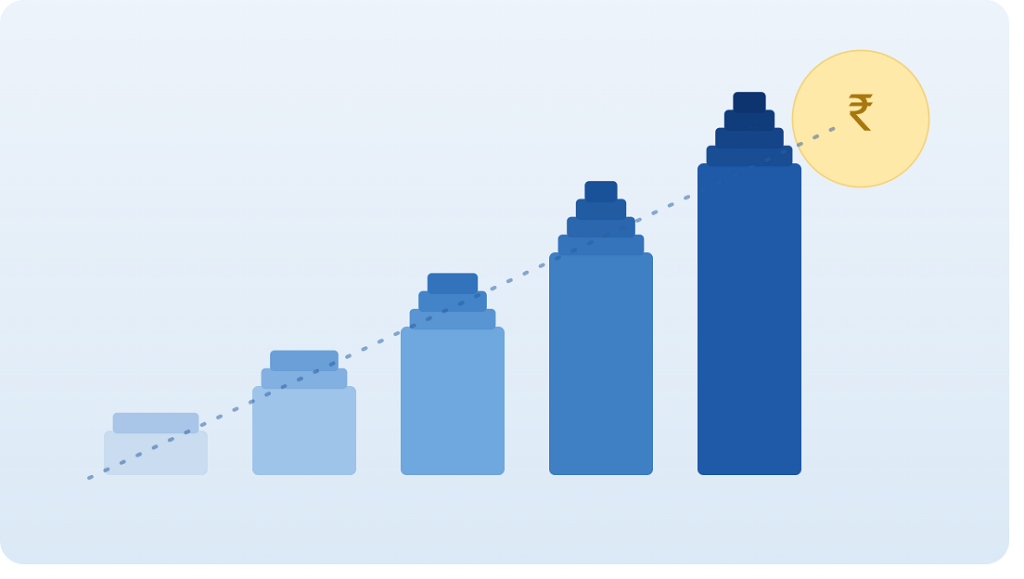
The real power of a small SIP shows up with time. The chart below compares the money you actually put in with what a ₹500 monthly SIP could be worth over different periods, assuming a return of 12% a year. That rate is only an illustration — real returns vary from year to year and are never guaranteed.
Illustrative projection using monthly compounding at an assumed 12% a year. Actual returns will differ and can be negative in the short term.
| Duration | Total Invested | Estimated Value | Estimated Gain |
|---|---|---|---|
| 5 years | ₹30,000 | ₹41,243 | ₹11,243 |
| 10 years | ₹60,000 | ₹1,16,170 | ₹56,170 |
| 15 years | ₹90,000 | ₹2,52,288 | ₹1,62,288 |
| 20 years | ₹1,20,000 | ₹4,99,574 | ₹3,79,574 |
| 25 years | ₹1,50,000 | ₹9,48,818 | ₹7,98,818 |
Notice how the gap between "invested" and "estimated value" widens fastest in the later years. That is compounding at work — and it is why starting early matters far more than starting big.
Step 1: Complete Your KYC
Before any SIP — regardless of the amount — you need a one-time KYC (Know Your Customer) verification. This needs your PAN card, an Aadhaar-linked mobile number for e-KYC, a photograph, and a cancelled cheque or bank statement. Most platforms complete this digitally in under 15 minutes, and once it's done, it's valid across every AMC in India. You can check your status anytime on the AMFI website. The KYC process is regulated by SEBI, and your records are held by KYC registration agencies such as CVL KRA.
Step 2: Set a Clear Goal for This SIP
Even a small SIP does better attached to a purpose — an emergency cushion, a gadget fund, or simply the start of a long-term wealth-building habit. Naming the goal makes it easier to pick a fund category in the next step and gives you a reason not to stop the SIP the first time markets dip.
Step 3: Pick a Fund Category That Suits a Small SIP
| Fund Category | Risk Level | Good Fit For a ₹500 SIP When… |
|---|---|---|
| Index Funds | Moderate to High | You want low-cost, broad market exposure without picking individual stocks |
| Large-Cap Equity Funds | Moderate to High | You want equity growth through relatively established, larger companies |
| Hybrid / Balanced Funds | Moderate | You'd rather have one fund that blends equity and debt automatically |
| Liquid / Debt Funds | Low | Your goal is short-term (under 2–3 years) rather than long-term growth |
For a first ₹500 SIP with a long time horizon, The right mutual fund category depends on your goal, investment horizon and ability to tolerate market fluctuations. A ₹500 SIP does not automatically mean that you should choose a particular category. For a beginner, it is useful to first understand the difference between categories such as equity, debt and hybrid funds, and then select a scheme that matches the purpose and time horizon of the investment. A small SIP should still be treated as a real investment decision rather than simply choosing a fund because its minimum SIP amount is ₹500.
Step 4: Choose a Direct Plan on a Platform or the AMC App
Every scheme comes in a Direct plan (bought straight from the AMC, no distributor commission, marginally lower expense ratio) and a Regular plan (bought through a distributor, with guidance built into a slightly higher cost). On a ₹500 SIP, the rupee difference in expense ratio is tiny in absolute terms, so the real question is whether Direct and Regular plans serve different investor preferences. Direct plans are purchased without distributor commission, while Regular plans involve distribution through an intermediary and may provide access to guidance or servicing. The appropriate choice depends on whether an investor wants to make fund-selection decisions independently or prefers professional/intermediary assistance.
Curious what a ₹500 monthly SIP could grow into over 10 or 20 years?
Try the SIP Calculator →Step 5: Set Up the SIP and Auto-Debit Mandate
Once you've picked a fund, the setup itself is short: select the scheme, choose "SIP" instead of "Lumpsum," enter ₹500 as the amount, pick a monthly date, and set up a NACH auto-debit mandate (a bank-mandate system run by NPCI) linking your bank account. This mandate is what lets the platform pull ₹500 automatically each month without you having to remember to transfer it manually — which is really the whole point of a SIP.
Step 6: Confirm Your First Instalment
After your first ₹500 instalment is processed, you'll get a confirmation along with a folio number for that investment — this is your reference for that specific fund holding going forward. It's worth keeping the confirmation email or SMS somewhere you can find it later.
Step 7: Stay Consistent — and Step Up Later
₹500 is meant to be a starting point, not a ceiling. Most platforms support a "step-up SIP," where your monthly amount increases automatically by a fixed sum or percentage each year as your income grows, without you needing to manually raise it every time. Starting at ₹500 and stepping up gradually is often easier to sustain than starting with a larger amount you can't comfortably maintain during a tighter month.
Amit starts a ₹500 monthly SIP at age 25. His friend Karan also starts at ₹500 but raises the amount by 10% every year. Both invest for 20 years at an assumed 12% return. By year 20, Karan is investing about ₹3,058 a month — still a modest sum once his income has grown.
| Amit (flat ₹500) | Karan (10% yearly step-up) | |
|---|---|---|
| Monthly SIP in year 20 | ₹500 | ₹3,058 |
| Total invested | ₹1,20,000 | ₹3,43,650 |
| Estimated value after 20 years | ₹4,99,574 | ₹9,94,436 |
How Rupee Cost Averaging Works: A ₹500 Example
A SIP invests the same amount whether the market is up or down. When the price (NAV) is low, your ₹500 buys more units; when it is high, it buys fewer. Over time, this evens out your average purchase cost. Here is a simple six-month illustration.
Hypothetical NAVs chosen to illustrate the concept — not the performance of any actual fund.
Over six months, the SIP invests ₹3,000 and buys 36.81 units. Your average cost works out to about ₹81.5 per unit, even though the average NAV over those months was ₹84.2. At the end, the NAV is back at ₹100, so your holding is worth about ₹3,681 — a gain of roughly ₹681. Someone who had invested the entire ₹3,000 in Month 1 at ₹100 would hold 30 units, still worth exactly ₹3,000 — no gain at all. The dip in Months 2–4 helped the SIP investor, not hurt them.
Common Mistakes With Small SIPs
- Pausing the ₹500 SIP the moment markets fall, which undoes the benefit of rupee cost averaging that small, regular investing is built around
- Treating ₹500 as "too small to matter" and never increasing it as income grows
- Starting several ₹500 SIPs in overlapping fund categories instead of one or two funds with a clear purpose
- Not setting up the auto-debit mandate, and relying on remembering to invest manually each month
Frequently Asked Questions
Can I really start a SIP with just ₹500?
Do I need a demat account for a ₹500 SIP?
Can I increase my SIP amount later?
What happens if I miss a ₹500 SIP instalment?
Is a ₹500 SIP safe?
How long should I continue a ₹500 SIP?
Can I stop or pause my SIP anytime?
Is SIP better than lumpsum for small amounts?
Can I start more than one ₹500 SIP?
AMFI-Registered Mutual Fund Distributor · ARN-167738 · Associated with Prudent Corporate
Content on this page is for general educational purposes and does not constitute personalised investment advice. See AMFI for official scheme and distributor information.
Disclaimer: This article is for educational and informational purposes only and should not be considered investment advice or a recommendation to buy, sell, or hold any mutual fund or security. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance is not indicative of future results.